Last updated November 18, 2026
Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Construction Emergency Preparedness Guide for Kendall Homes
Most Kendall homeowners prepare for a storm by buying water and batteries. Then the storm passes, a live oak branch opens the roof over the primary bedroom, and the real test starts. Here’s the part that surprises people: the way you document and authorize emergency repairs in the first 48 hours often decides whether your insurance claim pays or gets denied. We’ve watched South Florida adjusters approve claims with clean photo sequences and deny nearly identical damage where the paperwork was sloppy. This guide walks through the exact order of operations after construction damage hits a Kendall home, from the first photo to verifying a contractor’s license on your phone, so you don’t hand away your claim or your money.
Quick Answer
Construction emergencies in Kendall, FL (roof breaches, storm-driven water intrusion, tree or vehicle strikes) should be handled in a documented sequence: photograph and video everything before touching it, stop the water or cover the breach only with temporary measures, verify the contractor’s Florida license through DBPR before signing anything, and get an itemized written scope of the temporary work before it begins. Never sign an Assignment of Benefits at the door. The first 48 hours of documentation and authorized scope are what protect a Miami-Dade insurance claim from denial.
Styles & brands we work with
- Kitchen remodeling
- Bathroom remodeling
- Home additions & ADU
- Roofing
- Windows & doors
- Driveway & pavers
- Fence
Table of Contents
- The Documentation Sequence That Protects a Miami-Dade Claim
- How to Verify a Florida Contractor’s License in Hours, Not Days
- What an Assignment of Benefits Actually Transfers
- Pre-Storm Preparation: The Written Relationships That Matter
- Why Even Emergency Work Needs a Written Scope
- Water Intrusion: What to Do Before the Extraction Crew Arrives
- After the Temporary Fix: Planning the Permanent Repair
The Documentation Sequence That Protects a Miami-Dade Claim
The order of your photos matters, and almost nobody gets it right. Insurers reviewing a Miami-Dade claim want to see the damage in its pre-touched state before any repair, cleanup, or tarping. Take photos in this exact order before lifting a finger:
- Wide shots first: every room, from each doorway, before anything moves. These establish the context.
- Mid-range shots of the damaged area: the water stain, the broken window, the crack in the wall.
- Close-ups with a reference object: a ruler, a coin, or a shoe beside the stain or crack so scale is provable.
- A continuous video walkthrough narrating the sequence, from the front door to the back. Timestamped videos are harder to dispute than stills.
- Photograph the contractor’s license placard, the invoice, and the signed scope before work begins.
Kendall sits in unincorporated Miami-Dade, and the county’s building and permitting records are your reference point. If a contractor’s license is tied to a false business address, that mismatch shows up in a county search within minutes. Save a screenshot of the license verification with a date stamp. That screenshot is worth more in a claim dispute than any verbal assurance.
How to Verify a Florida Contractor’s License in Hours, Not Days
Storm season in Kendall brings out contractors from outside the county who show up at the door with a clipboard and a business card. Some are legitimate. Some are what the industry calls storm chasers, and a few of their “repairs” are exactly why insurers deny claims. You can verify a license in under five minutes using the Florida DBPR’s mobile lookup:
- Open the DBPR License Lookup on your phone’s browser.
- Enter the contractor’s name or company name. You can also look up the license type: Certified General Contractor (CGC), Registered Contractor (CRC), or Certified Roofing Contractor (CCC).
- Confirm three things: the license is current (not suspended or expired), the license is the correct type for the work (roofing work needs a roofing license, not a general handyman), and the license is active in Miami-Dade.
- Cross-check the name on the license against the name on the contract and the insurance certificate. A mismatch is a red flag.
- Screenshot the result with the timestamp visible. Save it to a folder named by date.
If the person at your door can’t provide a license number when you ask, stop there. No exceptions. In Kendall, several of the worst post-storm repair frauds we’ve seen started with a “courtesy” estimate that became a signed contract on a clipboard. The licensed professionals who show up with a written price up front are a different category entirely.
What an Assignment of Benefits Actually Transfers
An Assignment of Benefits (AOB) is a legal document, and signing one shifts your insurance claim to the contractor. That means the contractor gets paid by your insurer, not by you; they can negotiate, sue if necessary, and settle the claim on your behalf. It gives them standing in a claim dispute that was originally yours. In Florida, a series of post-2019 statutes tightened how AOB agreements work, but they did not eliminate them, and they did not eliminate unsolicited door-knocking.
What an AOB transfers in plain terms:
- Your right to negotiate the claim with the insurer.
- Your right to file suit if the claim is disputed.
- Often your right to receive payment directly.
The safest position after a storm in Kendall is to work with a contractor who does not ask you to sign an AOB. A legitimate contractor will bill you directly or bill your insurer through a direct-pay arrangement, but they won’t need ownership of your claim. If someone hands you an AOB at the door before you’ve even called your insurer, decline politely and close the door.
Pre-Storm Preparation: The Written Relationships That Matter
Emergency preparedness isn’t just a plywood list. It’s having a pre-qualified relationship with a licensed contractor before a storm hits. That relationship should include a written emergency response agreement that spells out response priority, the scope of emergency services they’ll provide (tarping, water extraction, board-up), and how their pricing works for emergency services. Pre-qualified bids from three separate contractors are worth more than one, because the day after a hurricane passes over Kendall, half the contractors in Miami-Dade are unreachable.
What a good pre-storm file should contain:
- A written emergency response agreement with at least one licensed general contractor.
- Copies of the contractor’s current license and insurance.
- Pricing for temporary tarping and board-up, in writing, with a per-square-foot number.
- Your homeowner’s policy number, adjuster’s phone, and a digital copy of the policy declarations page.
- A current video walkthrough of the home, stored off-site, from the last storm season. It’s the fastest way to prove pre-storm condition.
Build this file in the off-season, not in the hours after a warning is issued. Ask the contractor directly: “If a storm hits, what’s my response window, and what’s the protocol for your written price before work starts?” The answer tells you whether the relationship is real.
Why Even Emergency Work Needs a Written Scope
There is a common misconception that emergency work means acting first and paperwork later. That’s exactly the mistake that produces invoice shock. A signed, itemized authorization before emergency work begins is not a formality; it’s your protection against being handed a bill for work you never approved. We’ve seen Kendall homeowners billed for full roof replacement after authorizing tarping. The difference between a fair bill and a bad one is a written scope.
A proper emergency scope includes:
- A line-item description of the temporary work (e.g., “tarp 22 squares of shingle, 6 mil poly, mechanically fastened”).
- The specific price for each line, not a lump-sum range.
- A note that temporary work is separate from permanent repair, and that permanent repair will be quoted separately.
- The contractor’s license number and insurance citation on the same document.
- A signature line for the homeowner to acknowledge scope, not to transfer the claim.
This is The Kingswell Way in practice: say the price before the work, show up in the window we gave, leave the place cleaner than we found it. That applies to a two-hour tarp job as much as a full kitchen.
Water Intrusion: What to Do Before the Extraction Crew Arrives
After a storm in Kendall, water intrusion is the leading cause of secondary damage, and the leading cause of claim denials. The issue isn’t the water; it’s the mold that starts growing in 24 to 48 hours behind drywall and under flooring if the moisture isn’t documented and removed. Before a crew arrives, do this:
- Photograph the standing water, the wet drywall, and the wet flooring, in place.
- Shut off the power to affected rooms at the breaker. Do not wade into standing water near outlets.
- Move furniture and rugs out of the wet zone, and photograph what was there before you moved it.
- Place a box fan and open windows only if outdoor humidity is low and rain has stopped. In Kendall’s summer, it usually isn’t, and running a fan in high humidity makes the problem worse.
- Do not remove drywall or flooring yourself. Document it, and let the licensed contractor open up the wall so moisture readings are recorded.
If a contractor’s written scope doesn’t include moisture readings and a drying log, ask why. Mold is not covered by many homeowner policies the way sudden water damage is, and the difference between the two is documentation and drying time.
After the Temporary Fix: Planning the Permanent Repair
Once the tarp is on and the claim is filed, the real project begins. This is where homeowners get burned a second time: the same contractor who tarped your roof quotes a permanent repair at a price that balloons after demo. The protection is the same as it was for the emergency: a written price before any work starts, and a written guarantee on the finished work. For a full general contractor in Kendall, that standard covers the whole job, not just emergency services.
Permanent repair after a storm typically involves new roof decking, underlayment, and shingles. Material choice matters here: we install GAF and CertainTeed shingle systems, which carry their own manufacturer warranties alongside the workmanship guarantee. When you’re choosing between bids, ask for a line-item scope of the roofing system, not just a price per square. South Florida building code requires specific wind-uplift ratings in this zone, and a bid that skips that detail is a bid that will fail inspection. We pull the permits and pass the inspections, and that paper trail is part of the guarantee.
Common Mistakes to Avoid
- Signing an AOB at the door. A clipboard in your hand before you’ve called your insurer is a warning sign, not a courtesy.
- Photographing after the cleanup. Insurers can and do deny claims where the damage was photographed post-repair.
- Letting an unlicensed contractor tarp the roof. The tarp is a temporary measure, but a bad installation can cause further damage that isn’t covered.
- Skipping the license lookup because it’s “just a handyman.” Emergency work on a structural breach is not handyman work, and Florida law agrees.
- Running box fans in high-humidity Kendall summers. Fans move air, but in 90% humidity they push moisture into drywall, not out of it.
- Accepting a verbal scope. “We’ll tarp and see how it looks” is not a scope, and it will not hold up in a claim dispute.
- Waiting for the adjuster before stopping the water. The claim will fund the repair, but only if you’ve stopped the active damage first and documented it.
See the difference
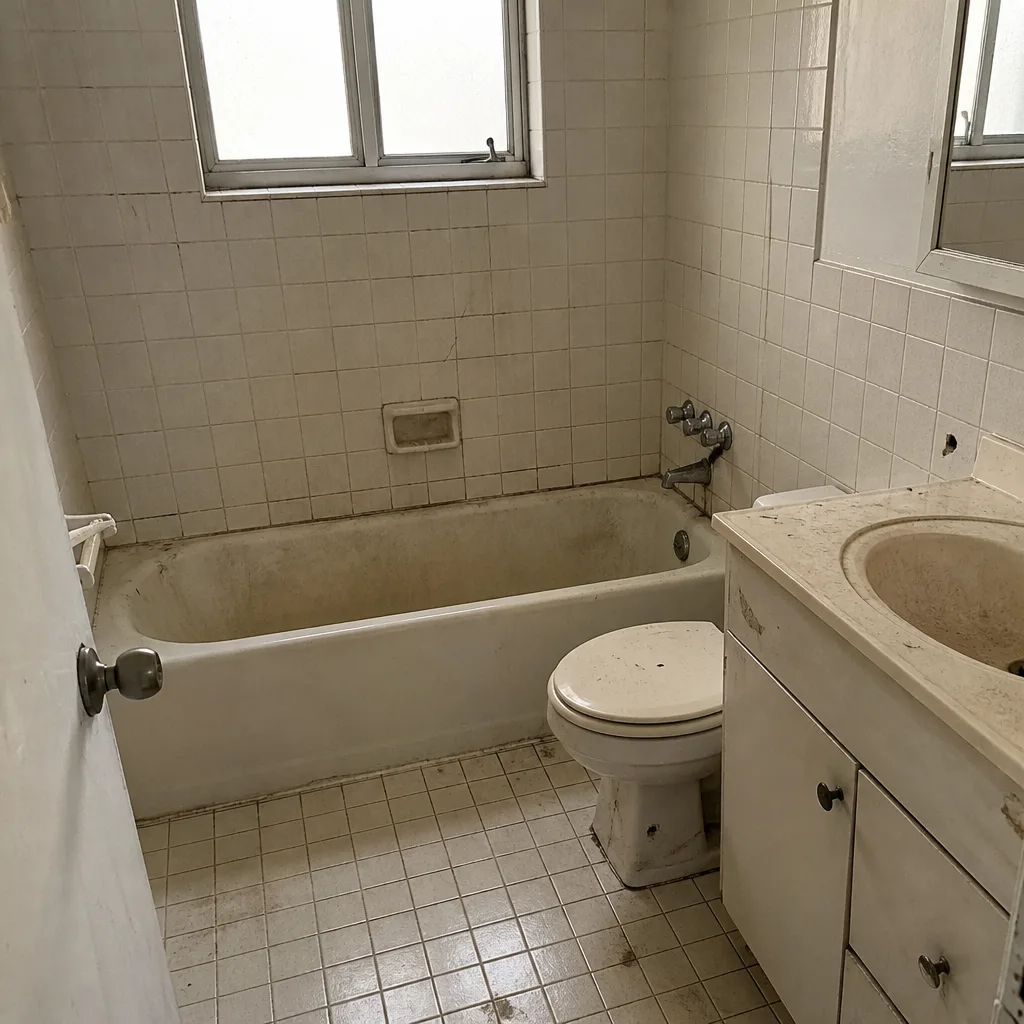 Before
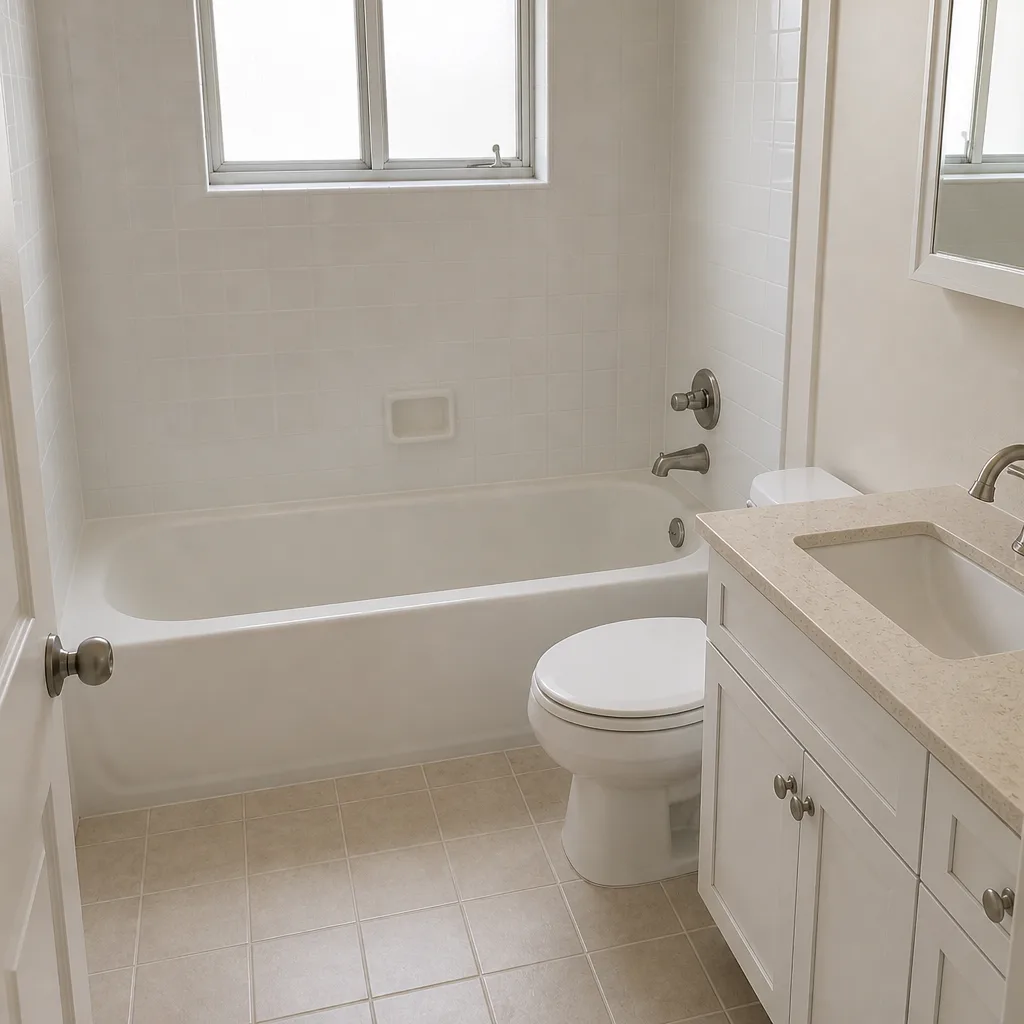 After
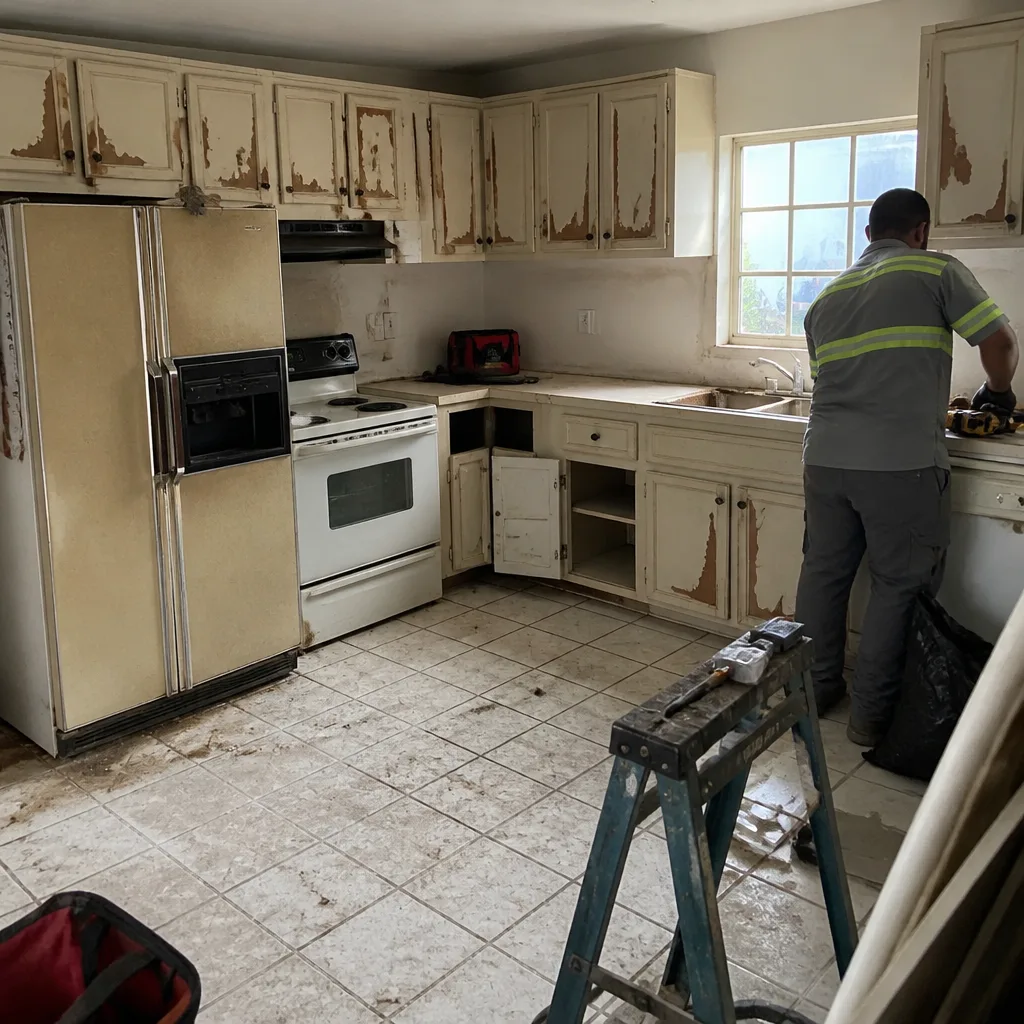 Before
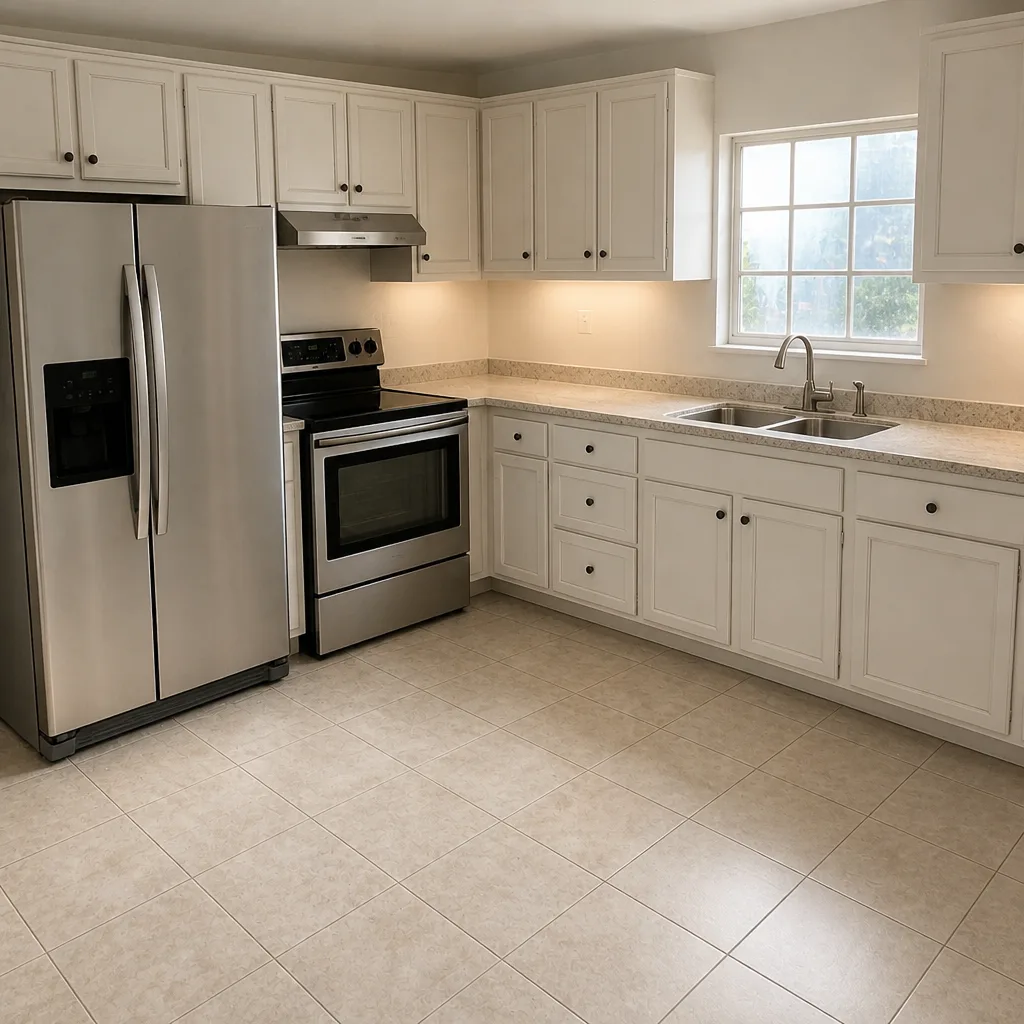 After
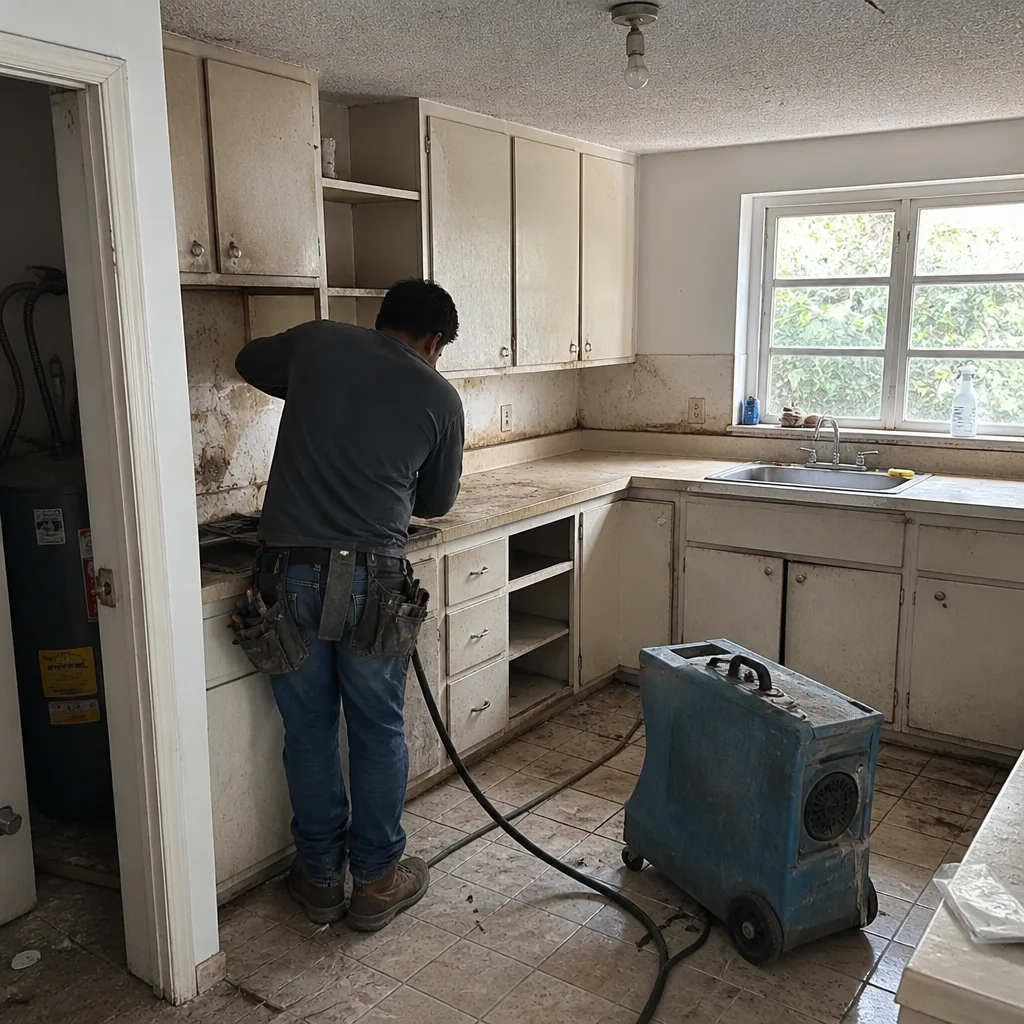 Before
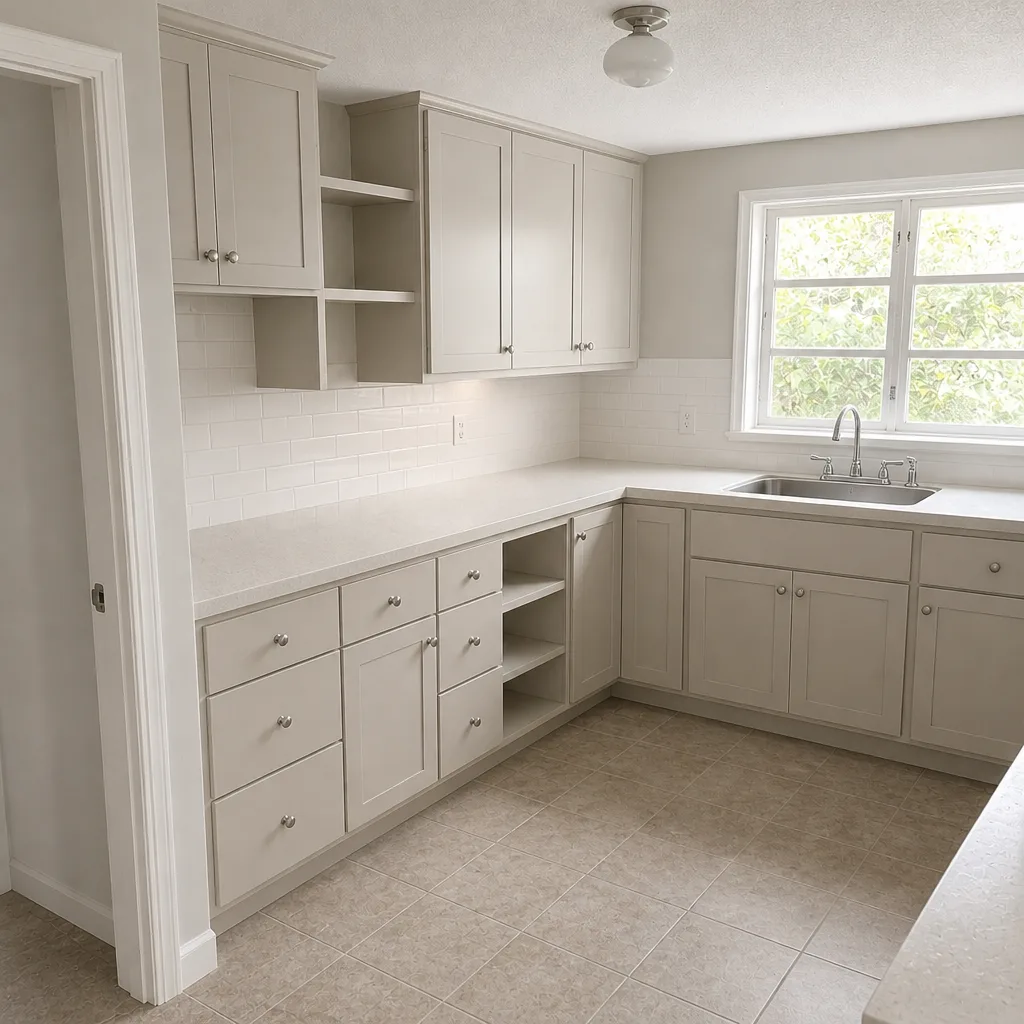 After
When to Call a Professional
Call a licensed professional immediately if a storm has opened your roof, a tree has struck the structure, standing water is inside the home, or any part of the building envelope is compromised. Those situations carry hidden structural and electrical hazards that aren’t safe to assess on your own. Call before you sign anything, before you allow anyone to remove debris from the structure, and before you approve any repair beyond tarping and extraction. A licensed Penhallow Remodeling Kendall home response starts with documentation and a written scope, not a clipboard. Penhallow Remodeling Kendall offers free estimates in Kendall, and we’ll walk you through the emergency sequence in plain terms. Call (844) 560-5417.
Frequently Asked Questions
Document the damage in this exact order: wide shots, mid-range, close-ups with a scale reference, then a video walkthrough. Do not touch or clean the damage before photographing. Then stop the water or cover the breach with temporary measures, and verify the contractor’s license through the Florida DBPR lookup before signing anything. Call (844) 560-5417 if you want us to walk through your documentation sequence.
Use the Florida DBPR License Lookup on your phone, confirm the license is current and of the correct type for the work, and screenshot the result with a date stamp. The whole check takes about five minutes. If the contractor can’t produce a license number when asked, walk away. Call (844) 560-5417 for a free estimate from a licensed Kendall team.
No. An AOB transfers your right to negotiate the insurance claim to the contractor, including the right to sue on your behalf. The safer position is to work with a contractor who bills directly and never asks you to sign one. If it’s offered at the door before your insurer has been notified, decline. Call (844) 560-5417 to talk through your situation.
Temporary tarping in Kendall typically runs $400 – $1,200 depending on roof size and access, and water extraction with drying equipment runs $1,500 – $4,500 depending on affected square footage. Both are usually reimbursable under a covered claim if documented properly. Get the number in writing before work begins. Call (844) 560-5417 for a free written estimate.
Often not. Insurers can deny claims where the emergency work was performed by an unlicensed contractor, especially if the tarping or extraction caused further damage. The license verification is not optional. Call (844) 560-5417 if you’re unsure whether the work was done properly.
Florida law generally requires you to notify your insurer of a storm claim within a specified window that has shortened in recent years. Don’t wait for a contractor’s estimate to file. Notify your insurer the same day you document the damage, and have the written scope ready to send. Call (844) 560-5417 for a written scope you can send to your adjuster.
The Bottom Line
The difference between a covered claim and a denial after a storm in Kendall comes down to the first 48 hours: the order of your photographs, whether you verified a license before signing, whether you signed an AOB, and whether the emergency scope was in writing. None of that requires a contractor in the door. All of it requires you to slow down by an hour before the tarp goes up. When the permanent repair comes, choose a Kendall kitchen remodeling or bathroom remodeling team only after the same documentation standard applies. The 365-Day Done Right Promise and the free return visit if a repair fails are part of every project we take on, in the storm season and out of it.
If a storm has already hit and you’re not sure what order to do things in, call Penhallow Remodeling Kendall at (844) 560-5417 to schedule your free estimate. A live person answers, day or night.
Written by the team at Penhallow Remodeling Kendall.